The Ten-Hour Claim
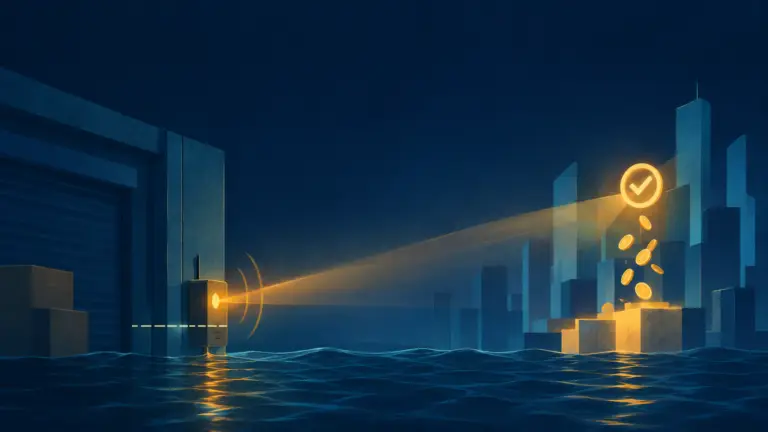
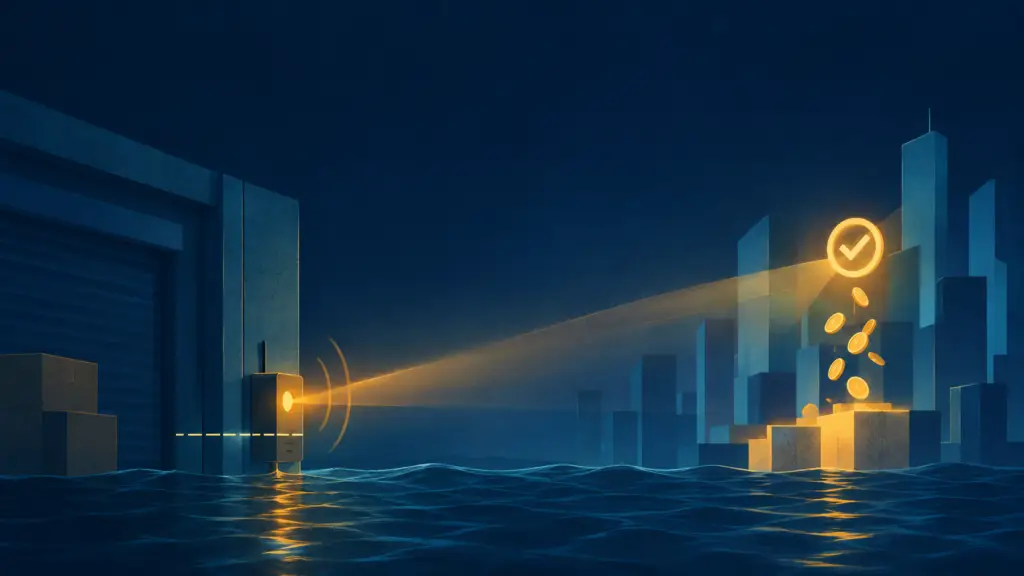
In November 2024, Storm Bert flooded a commercial property in the UK. The insurer, FloodFlash, had the claim assessed, approved, and paid in just over ten hours. No loss adjuster walked the site first. No forty-page claims form. A sensor detected water at a set depth, the policy’s trigger tripped, and the money moved.
Compare that to the industry norm. Property claims after a flood event routinely take weeks. Some take months, especially when adjusters are stretched thin across a whole region hit by the same storm. Ten hours isn’t a faster version of the same process. It’s a different business, wearing the word “insurance” as a disguise.
This issue is about that disguise. Not the version where analysts say “the industry is being disrupted” and move on. The specific version: which company, which product, which number, and what it means for the seat you sit in, whether that’s underwriting, distribution, or a portfolio.
The full model, not just the highlights
Strip an insurer down and there are four things it actually does. It builds the product. It decides what to sell. It decides how the product reaches a buyer. And it decides who buys. Call those four boxes production, offering, delivery, and markets.
Each box breaks down further, into three or four specific pieces. Production is technologies, processes, and assets. Offering is products, services, systems, and brand. Delivery is occasions, locations, and channels. Markets is customers, needs, and experiences.
Two things sit across all four boxes, connecting them. Pricing sits on top: new pricing strategies that price a different thing than the old model did. Partnerships sit underneath: new networks and partners, because almost none of the interesting products right now are built by one company alone. And when enough of these pieces change at once, in the same product, you don’t get an improved insurer. You get a new business model.
This issue goes through every one of those pieces, one at a time, with a real company and a real deal attached to each. Not a framework repeated back at you in the abstract. The specific version.
Production: technologies, processes, and assets
Start where the product actually gets made, because everything downstream depends on what happens here first. This box breaks into three pieces, technologies, processes, and assets, and this year all three are moving in insurance at the same time.
Technologies. Sixfold, an AI underwriting startup, launched what it calls a straight-through quote-and-bind capability for property and casualty insurers this year. The system doesn’t just flag risk factors for a human to review. It can carry a submission from intake to a bound policy without a person touching it, for the risks that fit clean patterns. Adnovum is now bringing that same engine to insurers across Germany, Austria, and Switzerland.
A second technology is doing the same thing for a completely different peril. ICEYE, which operates its own fleet of synthetic-aperture-radar satellites, sells flood and wildfire data straight into the insurance chain. Aon has partnered with ICEYE specifically to build flood and wildfire risk analytics from that satellite data. This is the same shift as AI underwriting, applied to the physical world instead of the paperwork: a machine reads the risk, at a resolution and speed no field survey could match.
Processes. The technology only matters if it changes how work actually gets done, step by step. Lemonade’s claims process is the clean example: submit, an AI reviews it against fraud and coverage checks, and in the cases that pass cleanly, it pays, all in the same short interaction. That isn’t a faster version of the old process. The old process had an adjuster in the loop by design. The new one doesn’t, for the claims where it doesn’t need one. That’s a redesigned process, not an accelerated one.
Assets. Sixfold recently added a capability it calls Institutional Intelligence, built to capture an individual insurer’s own underwriting history, the judgment calls a veteran underwriter has made for twenty years, and turn that into something the AI can draw on directly. That’s a carrier’s accumulated expertise, previously locked in one person’s head, converted into a reusable asset the whole underwriting team can use. FloodFlash’s own sensor network is the physical version of the same idea: hardware it installs at insured sites, which becomes both the claims trigger and a durable, hard-to-copy asset baked into every policy it writes.
Offering: products, services, systems, and brand
None of that production change means anything commercially until it shows up in what the company actually sells. The offering box is where it does, and the same two companies from the production section reappear here, because what an insurer can now build and what it can now sell are the same decision, not two separate ones. This box breaks into four pieces: products, services, systems, and brand.
Products. Gallagher, the giant broker, teamed up with FloodFlash this year to launch parametric flood cover specifically for golf courses: a segment with obvious, physical, easily-instrumented flood exposure and, historically, a miserable time getting standard flood coverage at a sane price. Notice what that product is not. It is not “better flood insurance for everyone.” It is flood insurance for one physical typology of buyer, priced against one measurable trigger, sold through one broker relationship.
Services. The product doesn’t stop at a policy document. FloodFlash installs and maintains the sensor at the site as part of what the customer is buying, which means the offering includes an ongoing service relationship, not a one-time paper contract. That single change, hardware plus monitoring bundled with risk transfer, is what makes a ten-hour claim possible at all.
Systems. The trigger mechanism itself, the sensor reading a water depth and automatically releasing a payout, is a system the customer is buying as much as they’re buying indemnity. Compare that to a standard policy, where the “system” the customer interacts with is a claims phone line and a PDF. The system is now part of the product’s value, not just the back office that supports it.
Brand. Lemonade has built its brand identity around the claim that got settled in two seconds, a story it still tells in its own investor materials years later. That’s a deliberate choice: the brand promise isn’t “we’re cheaper” or “we cover more perils.” It’s “you can trust the algorithm to pay you fast,” which is a completely different brand claim than the industry has historically sold, and one that only works if the technology and process underneath it are real.
Delivery: occasions, locations, and channels
A well-built product that nobody encounters at the right moment doesn’t move the top line. That’s why delivery matters as much as the product itself right now, and why the industry’s cost structure is quietly inverting: the channel used to be the most expensive part of running an insurer, and for the companies below, it’s becoming the cheapest part to add. This box breaks into occasions, locations, and channels.
Occasions. Cover Genius, which builds the technical plumbing that lets platforms sell insurance this way, raised $100 million this year specifically to expand AI-powered embedded protection. The occasion for buying insurance is no longer “I decided I need this.” It’s the moment of another purchase: booking a flight, financing a car, buying a piece of equipment, checking out on a marketplace. The insurance rides on an occasion someone else already created.
Locations. The most-cited number in embedded insurance right now is 76.38 percent: the share of embedded placements in 2025 that went through online, API-first channels rather than a person handing over paperwork. The “location” where insurance gets sold has moved from a branch or an agent’s office to a line of code inside someone else’s checkout flow.
Channels. Boost Insurance runs the backend infrastructure for MGAs and specialty brokers, and this year launched Boost Atlas, an AI-driven partner portal built specifically for that group. What it sells is the channel itself: a new MGA or broker doesn’t need to build underwriting operations, compliance, and carrier relationships from scratch, it plugs into Boost’s infrastructure and gets a working channel on day one. That’s the channel becoming a product in its own right, not just a route to market.
Markets: customers, needs, and experiences
Change where and when a product is sold, and you don’t just get more sales out of the same customers. You reach a different set of customers entirely, with different needs and a different idea of what a good experience even looks like. That’s this box, the one that finally answers who benefits from everything above it.
Customers. Golf courses that couldn’t get sane flood coverage. Gig workers who need coverage measured in shifts, not years. Small commercial accounts too minor to justify an underwriter’s afternoon under the old model. None of these are new people. They’re customers who were always there, priced out or ignored because no product was cheap or narrow enough to reach them.
Needs. The need being served is easy to misname. It looks like “protection from loss,” but for a small business, the real need is often cash-flow survival: a slow claim after a flood can bankrupt a business faster than the flood itself did, because rent, payroll, and suppliers don’t wait for a loss adjuster’s report. Parametric and AI-driven claims serve a need that indemnity insurance technically covers but has never actually delivered on well: money before the damage becomes a second disaster.
Experiences. The FloodFlash customer isn’t experiencing “insurance, but faster.” They’re experiencing something closer to how a modern claims process should have always felt: report the event, get paid, done. That experience, not the underlying technology, is what will actually move renewal rates and word of mouth in these niches over the next few years.
The pricing bridge: new pricing strategies
Four boxes down, and none of them yet explain why a customer agrees to pay what they pay. That’s the first of the two bridges connecting everything above, and it’s where the value created in production, offering, delivery, and markets actually gets captured in a price.
Traditional indemnity pricing is built around expected loss: how much will this policyholder likely cost us in claims, on average, across a large pool. The new pricing strategies running through every example above are built around something else entirely.
Usage-based auto insurance, telematics programs that price you on how you actually drive rather than who you statistically resemble, proved the model first, at consumer scale, years ago. It showed insurers that customers would accept being priced on measured behavior instead of demographic proxies, and that the data pipeline to do it reliably was buildable.
Parametric pricing takes that logic further: instead of pricing the probability of loss, you’re pricing the probability of the trigger, and selling speed and certainty as the product feature, not an afterthought. A buyer paying for parametric flood cover isn’t just buying “money if it floods.” They’re buying “money within hours, no argument, no adjuster.”
A third pricing strategy is showing up alongside the first two: continuous underwriting instead of annual renewal. When an AI underwriter like Sixfold’s can re-run a risk assessment cheaply at any time, instead of once a year at renewal, pricing stops being a once-a-year event and becomes something closer to a live feed. That’s a genuinely new pricing strategy, not a faster version of the old one, and it’s only possible because production got cheap enough to support it.
The partnership bridge: new networks and partners
Pricing answers what the customer pays. It doesn’t answer who actually builds and stands behind the thing being priced. That’s the second bridge, and it runs underneath every box already covered.
Look at every example above and count the companies involved in each one. FloodFlash plus Gallagher, the broker. Sixfold plus Adnovum, the systems integrator bringing it to European insurers. Aon plus ICEYE, the satellite data provider. Cover Genius plus every platform it plugs into, plus the carriers whose paper actually backs the risk. Boost plus the MGAs and brokers who use its infrastructure instead of building their own. Lemonade is the closest thing to a full-stack exception, and even it works with reinsurers to lay off risk.
The pattern: a carrier or reinsurer supplies capital and licensed paper. A technology company supplies the underwriting engine, the trigger data, or the distribution rails. A broker or platform supplies the relationship with the buyer. No single company in these deals owns all four boxes. That used to be seen as a weakness: fragmentation, too many hands in the deal. Now it’s the default architecture, because it lets each layer specialize in the one box it’s actually good at, and it lets new products launch in months instead of the years it takes to build underwriting, tech, and distribution in-house from scratch.
If you’re evaluating any new insurance product, partnership, or pitch, the honest question isn’t “is this innovative.” It’s “which of the four boxes does this specific partner structure actually change, and which one still runs on the old model underneath.”
New business models: when enough boxes move at once
That question, how many boxes actually changed, is the whole answer to what happens next. Change one box and you get a better feature. Change several boxes together, priced differently, built with the right partner, and you get something that doesn’t fit the old category of “insurance company” cleanly anymore. Four of those new shapes are visible right now.
Insurance-as-a-feature is Cover Genius’s model: insurance isn’t sold as a standalone product at all, it’s a checkbox inside somebody else’s transaction, and the platform hosting it never has to think of itself as an insurance company.
Underwriting infrastructure-as-a-service is Boost’s model: a new MGA or broker rents the backend, the compliance, and now an AI-driven partner portal, instead of building any of it. The company isn’t selling insurance so much as selling the ability to launch an insurance business quickly.
Underwriting-as-a-service is Sixfold’s model, and Adnovum’s role in bringing it to DACH insurers: the AI underwriter itself, including a carrier’s own captured institutional expertise, becomes a product other insurers license, not a system one company keeps to itself.
Sensor-plus-policy is FloodFlash’s model: the insurance product and a piece of physical hardware are sold and serviced together, so the company is part insurer, part IoT operator, and the two halves can’t really be separated anymore.
None of these four had an obvious name a few years ago, because none of them existed as clean categories. That’s what “new business model” actually means in practice: not a slogan, but a company that can’t be described using the org chart of a traditional insurer.
Where the money actually shows up
All of this, boxes, bridges, and business models, is only useful if it tells you where value gets created and captured. It does, in four specific ways.
New top-line growth is showing up in customer segments that were previously outside the addressable market entirely: golf courses, gig workers, small commercial accounts too minor for a traditional underwriter’s time. This isn’t stealing share from a competitor. It’s premium that didn’t exist as written business before, because no product was cheap or narrow enough to write it.
New cost reductions are showing up directly in loss ratios and claims-handling expense, where AI underwriting and straight-through processing cut the labor cost of evaluating and paying claims. That’s the mechanism analysts now point to when they explain Lemonade’s improving numbers, not as a side note but as the headline. Institutional Intelligence-style tools push the same cost line further, by cutting the time a senior underwriter spends re-explaining judgment calls the system can now hold onto itself.
New strategic premiums are showing up in markets where traditional indemnity insurers are retreating, climate-exposed property in particular, and parametric players are stepping in and charging for speed and certainty rather than apologizing for a narrower scope of cover. That’s pricing power in a market segment everyone else is fleeing, and satellite risk data from providers like ICEYE is what makes it underwritable at all.
New real options are showing up in the data and infrastructure itself. An insurer that builds a telematics pipeline for auto pricing, a trigger-monitoring sensor network for one parametric line, or an Institutional Intelligence layer for one underwriting team, now owns an asset it can point at the next product line almost for free. The infrastructure built for one narrow niche becomes the option to launch the next one faster than a competitor starting from scratch.
What to actually watch
If you’re underwriting or building product, the FloodFlash and Gallagher golf course deal is the template worth studying, not the headline worth skimming: a broad peril, narrowed to one physical customer typology, priced against one measurable trigger, distributed through one existing broker relationship. That’s a repeatable formula, not a one-off.
If you’re watching capital flows, Cover Genius’s raise, Sixfold’s funding rounds, and Boost’s expansion of its partner infrastructure are leading indicators of where distribution and underwriting infrastructure money is actually going. That’s worth more than a general “insurtech funding is up” headline, because each one tells you which specific box investors think is still underbuilt.
And if you’re watching public numbers, Lemonade’s loss ratio trend matters more than its premium growth number right now. Growth is easy to buy. A loss ratio that keeps improving while AI does more of the underwriting and claims work is the number that tells you whether the production-box argument actually holds up once real money and real claims run through it.
The insurer that pays a claim in ten hours isn’t doing customer service better. It rebuilt what it produces, what it offers, how it delivers, and who it sells to. It priced the whole thing differently, and built it with partners instead of alone. That’s not a nicer version of insurance. It’s a different business that happens to still be called insurance, and it’s worth knowing which piece of your own book of business hasn’t been rebuilt yet.
Working session: map your own four boxes
Reading through six boxes and bridges is one thing. Testing them against your own book of business is another, and it takes less time than this issue did to read. Bring this to your next product or portfolio meeting. Pick one product line, one book of business, or one broker relationship. Fill in the table out loud, in the room, together. Don’t let one person fill it in alone beforehand. A vague answer, or two people writing different answers to the same box, tells you more than a clean answer would.
| Box | Question to answer out loud | Where we stand today | One action for this quarter |
| Production | What does it cost us, in hours or dollars, to underwrite one submission end to end? | ||
| Offering | Could a machine read our claims trigger off an instrument, or does it need a human judgment call every time? | ||
| Delivery | What share of our policies are sold at the moment of another purchase, versus as a standalone errand? | ||
| Markets | Name one customer segment we turn away today that a narrower, cheaper product could serve. | ||
| Pricing model | Are we pricing expected loss, or could we price the certainty and speed of payment instead? | ||
| Networks and partners | Which box above would move fastest if we brought in a partner instead of building it ourselves? |
Set a date, thirty or sixty days out, to come back to this same table with the “today” column filled in as a “then” column. If nothing moved, that’s the finding. Say so, and pick the box you’ll actually act on next.
References:
- Embedded Insurance Market Outlook: 30%+ CAGR Forecast Through 2031; Online and API-First Placements Held 76.38% Share in 2025 (Mordor Intelligence)
- FloodFlash pays parametric UK Storm Bert flood claim in just over 10 hours (Artemis.bm)
- Gallagher teams with FloodFlash to launch parametric flood cover for golf courses (Artemis.bm)
- 2026 Parametric Insurance Market Report: Industry Set to Reach US$7.64 Billion by 2031 (GlobeNewswire)
- Cover Genius lands $100m to power AI embedded protection (fintech.global)
- Lemonade’s Improving Loss Ratio Is the Real Story (The Motley Fool)
- Sixfold launches AI Underwriter for P&C insurers (fintech.global)
- Adnovum to bring Sixfold’s AI underwriting to DACH insurers (fintech.global)
- InsurTech firm Sixfold secures $30m to advance AI underwriting (fintech.global)
- Sixfold upgrades underwriting brain with Institutional Intelligence (fintech.global)
- Sixfold’s AI Underwriter Turns Carrier Expertise Into Machine Memory (actuary.info)
- Aon and ICEYE join forces to revolutionise flood and wildfire risk analytics (The Insurer TV)
- SAR Satellite Data Enables New Parametric Flood Insurance Products (ICEYE)
- Boost Insurance Launches Boost Atlas: The AI-Driven Partner Portal Built for Specialty Commercial Brokers & MGAs (Business Wire)
- Boost Insurance Expands Its Infrastructure-As-A-Service Platform (Pulse2)